In conventional commercial banking, a personal loan consists of borrowing direct paper currency and repaying that principal alongside accrued interest (Riba). Under Islamic jurisprudence, money cannot generate profit merely by lending money.
To provide legitimate, clean liquidity for retail customers needing cash for weddings, medical treatment, education, or emergency expenses, Faysal Bank (Faysal Islami) operates its personal financing under the globally recognized Shariah structure of Tawarruq (facilitated commodity Murabaha).
Below is an itemized breakdown of how the Tawarruq contract operates step-by-step, official financing parameters, borrower eligibility, and Schedule of Bank Charges (SOBC) fee rules.
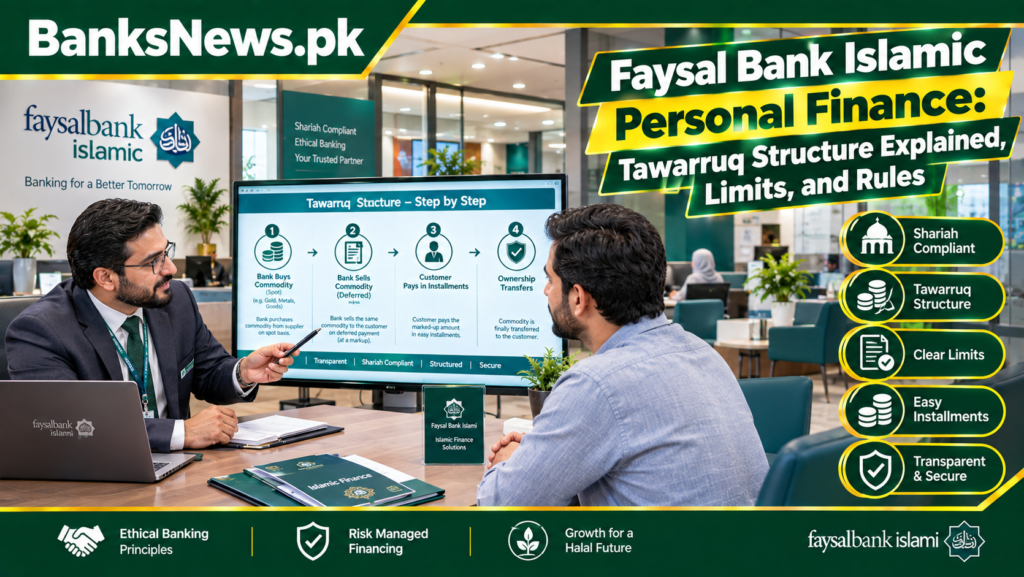
Understanding the Tawarruq Structure (Step-by-Step)
Tawarruq (Monetization) is a series of independent purchase and sale contracts involving Shariah-compliant physical commodities (such as verified metals or agricultural commodities traded on international or local exchanges like the Pakistan Mercantile Exchange – PMEX).
The entire transaction is executed electronically in four distinct stages:
[1. Commodity Purchase]
Bank buys physical commodities from an Open Market Broker on spot payment.
         │
         ▼
[2. Murabaha Sale to Customer]
Bank sells commodities to Customer at Cost + Agreed Profit, payable in deferred monthly installments.
         │
         ▼
[3. Agency (Wakalah) Authorization]
Customer appoints the Bank as an Agent (Wakil) to sell the commodities to a 3rd Party Broker.
         │
         ▼
[4. Cash Credit into Customer Account]
Broker purchases goods; Sale proceeds (cash) are deposited directly into Customer's checking account.
- Spot Purchase by Bank: Faysal Bank purchases an agreed volume of tangible commodities from an independent international/local commodity supplier on a spot-delivery, spot-payment basis. The bank takes legal ownership and constructive possession.
- Murabaha Sale to Customer: The bank sells the owned commodities to you at an agreed purchase price (Principal Cost + Declared Fixed Profit Margin), payable over a designated tenure (e.g., 12 to 48 months) in fixed monthly installments. At this point, you become the legal owner of the physical goods and owe the deferred Murabaha debt.
- Appointment of Agent (Wakalah): Because you need liquid cash rather than industrial metal or agricultural goods, you execute an agency contract (Wakalah) authorizing the bank to act as your agent to sell those commodities in the open market on your behalf.
- Liquidity Disbursement: The bank sells the commodities to a third-party broker for cash. The cleared sales proceeds are immediately deposited directly into your checking account as liquid funds.
Financing Parameters & Product Terms
| Product Feature | Unsecured / Clean Variant | Secured Variant (Term Deposit / Collateral) |
| Islamic Contract Mode | Tawarruq / Commodity Murabaha | Tawarruq / Commodity Murabaha |
| Financing Limit | PKR 50,000 up to PKR 4,000,000 | Up to PKR 7,000,000 (or 85% of collateral value) |
| Repayment Tenor | 1 to 4 Years (12 to 48 Months) | 1 to 5 Years |
| Pricing Nature | Fixed Profit Rate over the entire selected tenure | Discounted Fixed Profit Rate |
| Security / Collateral | None (Clean Lending; based on income cash flows) | Hypothecation / Lien over Faysal Islami TDR or deposits |
| Takaful Benefit | Built-in Takaful (Islamic life cover) during tenure | Complimentary Takaful coverage |
Eligibility Criteria
To qualify for Faysal Islami Personal Finance, applicants must meet the bank’s underwriting criteria:
- Customer Segment: Confirmed salaried professionals whose monthly salary is credited directly into a Faysal Bank account (or approved corporate payroll tie-up).
- Minimum Net Monthly Salary:
- Permanent Salaried Employees: Minimum PKR 35,000 to PKR 45,000 / month (varies by employer company tier).
- Contractual Staff: Minimum PKR 75,000 / month with 2 years of continuous contract vintage.
- Age Limits:
- Minimum: 21 years at time of booking.
- Maximum: Up to 60 years (or official retirement age) at loan maturity.
- Debt Burden Ratio (DBR): Total monthly debt amortizations across all cards and consumer loans cannot exceed 40% of verifiable net monthly income under SBP regulations.
- Credit Standing: Zero active defaults or write-offs on the SBP e-CIB report over the last 24 months.
Mandatory Documents Required
- Verified copy of valid CNIC / NICOP.
- Signed Personal Finance Application and Tawarruq Offer & Acceptance documents.
- Latest 3 months’ official pay slips stamped by employer HR/Payroll.
- Employment verification letter confirming designation, joining date, and retirement year.
- Official 6 to 12 months’ bank account statement showing clear payroll entries.
Fees, Charges, and Shariah Charity Clauses
Unlike conventional loans that levy interest penalties for delayed payments, Faysal Islami enforces Shariah-compliant charge structures:
- Application Processing Fee: As per the official Islamic Schedule of Charges (typically PKR 7,000 to PKR 10,000 + FED or 1.2% of financing amount).
- No Compound Penal Interest: If an installment is delayed, the customer is billed a late payment fee, which is transferred strictly into a registered Shariah Charity Fund to support social welfare, completely separate from bank earnings.
- Early Buyout / Early Settlement: The customer can pay off the outstanding balance before maturity. While the Murabaha price is legally fixed, the bank grants a voluntary rebate/discount (Ibra) on unearned future profit at its discretion in accordance with SBP Shariah guidelines.